Dubai Post-Handover Payment Plan: The Cash Burden Most Buyers Don’t Model
Most buyers treat a post-handover payment plan as a price concession. It is not. The developer defers a portion of the purchase price past delivery, but the total obligation does not change.
Updated 12 October 2026
Most buyers treat a post-handover payment plan as a price concession. It is not. The developer defers a portion of the purchase price past delivery, but the total obligation does not change. You take possession of the unit while a balance — sometimes 30% or 40% of the purchase price — remains outstanding on a fixed schedule. The signed sale and purchase agreement sets the triggers, amounts, and the consequences if you miss them.
Whether you can carry that balance is not a question the developer's schedule answers for you. It depends on your liquidity, the timing of your rental income, whether a lender will finance any part of it, and how those three things interact under pressure. The methodology in this article works through each in sequence, before you sign — not after you take the keys.
Build a dated cash-flow map from the SPA
A sound financial model requires mapping every payment date and trigger against your available cash. List every payment amount, due date, condition, and expected funding source directly from the SPA to create an accurate timeline. Treat calendar-based dates and construction-progress triggers as entirely distinct events. A contract stating payments are due after handover does not necessarily mean the schedule waits until a tenant moves in or the building is fully operational, as the document specifies the exact event that starts the clock.
Model your potential funding structures based on three distinct scenarios. In the first, you pay developer installments only: the post-handover balance remains payable directly to the developer according to the SPA schedule, funded from cash reserves or rental income. In the second, a mortgage replaces the developer balance: mortgage proceeds pay off the developer in full at handover, and you then service standard monthly mortgage payments to the bank, removing the developer from the equation. In the third, both obligations run concurrently — you make payments to the bank for the financed portion and to the developer for any remaining scheduled installments, provided the SPA and the lender permit this arrangement.
Avoid double-counting your capital across these scenarios. If you expect a mortgage to clear the developer balance, you cannot allocate that same cash reserve to furnishing, transfer fees, or living expenses.
To map this properly, use a specific calculation sequence. The post-handover balance equals the purchase price multiplied by the contracted post-handover percentage. The net rent available for debt service equals the collected rent minus vacancy allowances and owner-paid operating costs. Your monthly shortfall is the developer installment, plus any mortgage payment, plus costs not already deducted, minus that net rent. Finally, your handover cash gap includes the final or balloon payment, plus all costs due at handover, minus approved and drawable mortgage proceeds, minus liquid funds available above your protected reserve.
The dates matter as much as the totals. Some developers structure post-handover plans as 1% a month for a set period, while others demand heavy quarterly payments. A schedule tied strictly to calendar months forces you to pay even if handover is delayed, whereas a schedule tied to construction milestones shifts with the building's progress.
| Schedule Type | Payment Trigger | Cash Flow Implication |
|---|---|---|
| Calendar-tied | Specific dates (e.g., 1st of every month) | Payments fall due regardless of construction delays. You may pay post-handover installments before receiving the unit. |
| Milestone-tied | Construction progress or handover notices | Payments delay if the project delays. You align cash outflows with physical asset delivery, but dates remain unpredictable. |
Stress-test rental cash flow against the installment
Base your stress test on collected rent, not a headline yield or an advertised gross rent. Calculate the net figure after accounting for readiness, snagging, furnishing, leasing time, vacancy, collection risk, service charges, management fees, and maintenance.
An illustrative calculation reveals the cash burden. Assume a AED 2,400,000 purchase with a 30% post-handover balance, making the deferred portion AED 720,000. If the developer splits this into 24 equal monthly installments, the obligation sits at AED 30,000 a month.
If the assumed net rent reaches AED 15,000 a month, the rental income covers half the installment, leaving a AED 15,000 monthly cash shortfall that requires other funding sources. A newly handed-over unit rarely generates rent immediately. If the first rent arrives three months after handover because of snagging, furnishing, and finding a tenant, the first three installments demand AED 90,000 in cash before any rent collection. You will also need to add handover costs, furnishing expenses, and initial service charges to that upfront cash requirement.
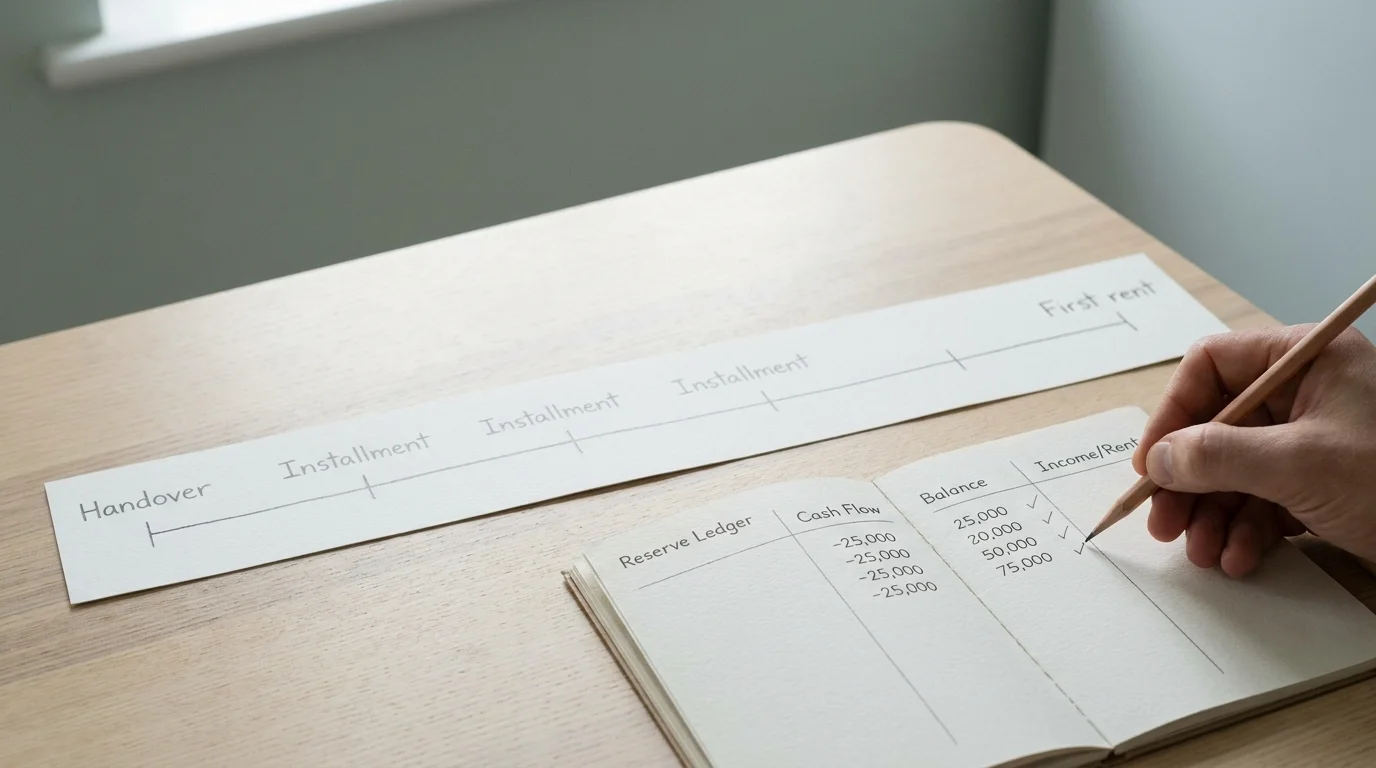
These figures are strictly illustrative and do not represent Dubai market averages or typical developer splits. Rerun the test with the exact SPA schedule and defensible rent assumptions. While RERA index tools can inform a benchmark, they do not establish the exact rent a new unit will achieve upon delivery.
Owner-paid costs heavily impact the net figure. You will need to subtract Dubai Land Department registration fees for the tenancy contract, building service charges calculated per square foot, property management fees, typically a percentage of the gross rent, and an annual maintenance reserve. If you plan to occupy the unit yourself, run the model with zero rental income. A buyer assessing a Dubai off-plan property investment needs to prepare for delayed rent or lower-than-expected yields without defaulting on the developer schedule.
Count mortgage funds only when the lender confirms them
A developer's payment schedule is not a mortgage approval. A lender separately assesses your repayment capacity, eligibility, the property status, and its valuation. The lender dictates the conditions and timing for drawdown, entirely independent of the developer's demands.
Treat a mortgage estimate or pre-approval as uncommitted until the bank confirms the exact amount, conditions, and availability for your specific transaction. Include a no-mortgage scenario and a lower-valuation scenario in your stress test because valuation risk is a major factor at handover. If you bought the unit at a premium, the bank's independent valuer might appraise it lower than the purchase price upon completion. The bank calculates the loan-to-value ratio based on the lower of the purchase price or the current valuation, and a low valuation forces you to bridge the gap with additional cash, placing immediate stress on your reserves.
Overseas buyers can obtain financing, but the terms are highly specific to the individual. An institution advertising a home-loan offering for non-residents shows that these products exist in the market, though it does not guarantee that a particular investor or off-plan unit qualifies. Obtain written terms from a lender based on your residency, income, liabilities, and the lender's valuation of the property.
Central Bank of the UAE (CBUAE) regulations govern domestic mortgage lending. The CBUAE Rulebook displays a consolidated version dated April 8, 2020, which includes loan-to-value ceilings, maximum tenors, and rate-stress testing rules. Because regulations and bank policies change, verify current numerical caps and lender terms directly with a bank rather than relying on older limits.
Budget for the finalized transaction and registration costs. The Dubai Land Department lists a fee of 0.25% of the mortgage value for an ordinary mortgage with an ordinary or usufruct title deed. The same service page lists an AED 4,000 service-partner fee plus VAT and, for provisional Oqood registrations, an AED 5,000 fee plus VAT; it also requires an e-NOC from the developer for provisional sale properties. Because the page lists different charges by registration route, confirm the applicable route and current fees before setting your handover budget.
I can help align these financing realities with your capital limits by matching your liquidity thresholds against the SPA due dates and lender conditions to compare funding scenarios. Because only your lender can confirm the financing, I build the acquisition strategy around the funds you control directly.
Escrow and payment triggers
Dubai real estate law places regulatory controls on developer funds. Dubai Law No. (8) of 2007 applies to developers selling off-plan units who receive purchaser payments. The DLD states that off-plan buyer payments are deposited in the project escrow account dedicated to that specific development.
While escrow provides a necessary structure for development funds, it does not act as a guarantee of your rental income, mortgage approval, investment return, or personal ability to meet the schedule. Confirm the payee and exact payment treatment for your particular SPA. The DLD separately describes a post-completion project escrow-settlement service, so you cannot assume every installment due after handover remains in the exact same construction-stage escrow arrangement.
If your schedule is tied to construction milestones, DLD guidance says an investor can request confirmation of the current completion percentage from the DLD-approved project consultant and track the project status. For completion-based payment schedules, DLD says the investor is not obligated to pay in response to a developer's payment request unless a letter from that consultant confirms the agreed stage or percentage has been reached.
Default, registration, and exit rights
Missing a payment under an off-plan sale contract or transferring an off-plan unit is subject to statutory procedures, and Dubai Law No. (13) of 2008 sets out the Interim Property Register requirements. Under that law, dispositions of off-plan units must be entered in the Interim Property Register, while an unregistered sale or other legal disposition that transfers or restricts ownership or ancillary rights is void.
Developers heavily restrict early exits. A developer will not issue an NOC for resale if the buyer is in arrears. Many contracts require 30% or 40% of the total purchase price to be paid before the developer permits any resale, restricting undercapitalized buyers who thought they could quickly assign the property before handover or exit early in the post-handover phase.
Late payments trigger material consequences. Dubai Law No. (19) of 2020 amended Article 11 of the 2008 law, setting out a formal process involving notification to DLD, with remedies varying according to project completion and other specific conditions.
The legislation distinguishes different scenarios based on progress. The text sets different available remedies when a project is more than 80% complete, between 60% and 80% complete, or below 60% after construction has begun. Depending on the tier and the statutory conditions, remedies can include a claim for the balance, a public auction, or termination of the contract with the developer retaining a specified percentage of the property value. Certain no-work or cancellation circumstances carry their own treatments under the law.
Because these tiers and formal procedures exist, default cannot be reduced to a single forfeiture percentage or a universal grace period. The specific facts of your purchase, the SPA terms, and the formal notification procedure dictate the outcome. Check your contract for resale rules, NOC requirements, and balance-settlement terms before you commit capital. Seek legal advice for disputed delays, payment issues, or termination threats, particularly if you are trying to capitalise on distressed deals where existing buyers have missed their scheduled installments.
Set your reserve threshold and know when to wait
A sound property acquisition requires a decision-focused stress test before you sign the SPA. Delay the handover date in your spreadsheet and check which SPA payment dates move with it. Factor in a unit that is not immediately rentable due to snagging or market conditions. Lower the expected rent, delay its start date, and completely remove any unconfirmed mortgage proceeds from your available funds.
Add all associated costs to the handover period. Include the final SPA payment, furnishing expenses, initial service charges, mortgage registration fees, utility connection costs, and move-in fees. If you might need to exit the investment before the payment plan ends, add the costs and conditions of assignment, including the developer's NOC and any requirement to settle a large percentage of the balance before resale.
Set a buyer-specific liquidity floor that covers your chosen no-rent and financing-delay scenarios while keeping funds available for your other life obligations. Reject the idea of a universal reserve percentage. A payment plan should not depend on immediate maximum rent, aggressive bank leverage, or rapid price appreciation to keep you solvent. If you intend to fund a monthly shortfall from other assets, quantify that exact cash drain against your overall liquidity and intended holding period.
Sometimes the numbers show too much exposure. When a purchase leaves no room for delayed rent, unexpected costs, or denied financing, waiting or walking away is the correct decision. Post-purchase stewardship requires you to track collected rent, actual operating costs, upcoming developer installments, and the viability of your exit options. An acquisition is only successful if you can hold the asset comfortably through market fluctuations.
I work through a five-stage process — diagnose, align, prepare, execute, and steward — starting with your liquidity thresholds, not the available inventory. I provide fiduciary-aligned advice, helping you build a clear portfolio strategy and exit plan based on evidence. My off-plan advisory service may be compensated through developer commissions, while secondary-market transactions carry a stated 2% fee. This ensures I dedicate time to downside-scenario modelling, SPA review, and long-term post-purchase monitoring, aligning the acquisition with your risk tolerance rather than a launch calendar. Visit ritukant.com to test your parameters.